All Categories
Featured
Empathy-Driven Medical Underwriting Best Practices

Reviewing Traditional Versus Specialized Coverage

Empathy-Driven Medical Underwriting Best Practices
Table of Contents
The business you use to for life insurance coverage will ask about your household's medical history. Age Age16 2021 2425 3435 4445 5455 6465 +Coverage Amount Protection AmountUnder$50,000 $50,000$100,000$100,000 $200,000$200,000 $300,000$400,000 $500,000$500,000 $1,000,000$1,000,000 $2,000,000$2,000,000 $5,000,000$5,000,000+ Coverage Type Protection TypeWhole LifeTerm LifeFinal ExpenseNot Sure Gender GenderMaleFemaleNon-Binary Shivani Gite is an individual financing and insurance coverage author with a degree in journalism and mass communication.
A cancer diagnosis can bring a whirlwind of emotions and unpredictabilities. While your concern is likely your health and treatment, it's natural to think of the futureincluding your loved ones' financial wellness. Life insurance can provide monetary security and defense for your family. You may wonder: can you get life insurance if you have cancer? While purchasing a life insurance policy after a cancer medical diagnosis provides some challenges, alternatives exist.
Some medical conditions, including cancer, are thought about pre-existing. Life insurance business thoroughly evaluate each case, considering a few elements.
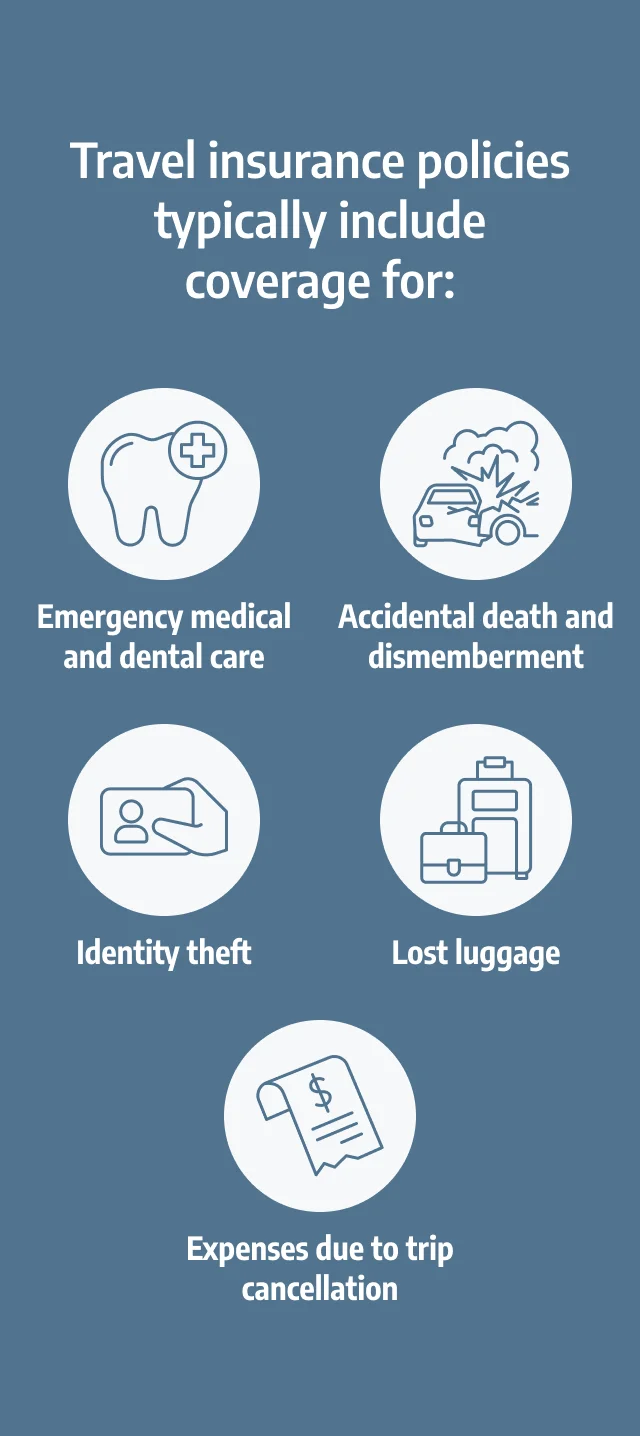
Obtaining Health Safety for Global Trips Abroad
If you already have life insurance coverage, a new cancer diagnosis generally will not impact it. Guaranteed Approval Life Insurance coverage So, can you get life insurance if you have cancer?

Approval is guaranteed despite whether you have health conditions like cancer. Compared to other types of life insurance coverage, guaranteed acceptance policies may have lower protection quantities and higher monthly premiums. Streamlined concern life insurance coverage policies typically have a less strenuous application process than conventional protection types. You typically require to respond to some standard health concerns but don't need a medical examination.
Many employers provide group life insurance coverage as part of their benefits bundle. This term coverage can be available for cancer patients or survivors as it typically has minimal health requirements, consisting of no medical questions or health exams. Nevertheless, group life insurance typically provides lower protection quantities than private policies you purchase yourself.
Impaired Risk Specialized Coverage(in the case of whole life). The application procedure is usually more extensive and involves a medical exam.
Funding the Support Trust Through Life Insurance
Finding the best life insurance coverage business after a cancer medical diagnosis is vital. Here are some essential factors to think about when shopping for life insurance. Examine the insurance company's financial rankings with agencies like AM Best to assess its stability. Read client evaluations to understand its general credibility. Discover insurance companies or agents who focus on life insurance coverage for people with pre-existing conditions like cancer.
Do not think twice to get as much info as you require from the insurer. Inquire to describe policies, prospective exclusions, and costs upfront. Navigating life insurance with a cancer diagnosis can feel overwhelming, you have alternatives. Research the offered policies, compare quotes, and deal with the best insurance agent to find protection that aligns with your needs.
Click here to discover more. [skyword_tracking/] When a life insurance coverage business rejects a claim and cancer is part of the reason, households are typically left without the death benefit they were counting on and without a clear description of what takes place next. Insurers normally cite misrepresentation, material omission, or a policy exclusion, and they send out a denial letter that can seem like the final word.
Wisconsin law gives insurance policy holders and beneficiaries the right to contest a denial. Insurers that deal with claims in bad faith, indicating they reject without a genuine basis, hold-up unreasonably, or misrepresent policy terms, can deal with liability beyond just the original claim amount. Whether a denial increases to that level depends upon the specific truths, including what was divulged, what the medical records reveal, and how the insurer conducted its review.
We have likewise seen disagreements including objected to medical records, contrasting physician declarations, and insurance providers who moved money straight to a return-of-premium position without adequate examination. At Wallace Law, we deal with insurance policy holders and recipients who have actually been denied, delayed, or misinformed by insurance companies after a cancer-related claim. We concentrate on first-party insurance claims and bad faith insurance practices.
Securing Medical Coverage for Global Travel Abroad
A cancer medical diagnosis changes whatever including your monetary concerns. Among the first concerns lots of clients and families ask is: The truthful answer is: it depends, however you nearly definitely have more choices than you believe. This guide covers everything you need to learn about and from what kinds of policies are still readily available, to the length of time you may require to wait, to what it will cost, and what options exist if conventional protection isn't an option today.
We'll cover those options too. Quick response: Yes, however during active treatment, your options are restricted to guaranteed concern policies, group employer coverage, and last expenditure insurance coverage. Cancer survivors who are 210+ years in remission may get approved for conventional policies at higher-than-standard rates. If you are presently undergoing chemotherapy, radiation, surgery, or other cancer treatments, a lot of conventional life insurance coverage companies will for term or whole life insurance.
Nevertheless, "can I buy life insurance coverage if I have cancer" and "can I get life insurance coverage if I have cancer" are not the like "do I have zero options." Throughout active treatment, you can still access: no medical examination, no health concerns, approval ensured within eligible age ranges generally offered throughout open enrollment regardless of health status created for individuals with severe health conditions, usually $5,000$25,000 in protection doesn't cover death from disease, however might be offered and adds some monetary protection In addition, if you currently have a life insurance policy, your medical diagnosis may permit you to trigger accelerated survivor benefit, pursue a Living Benefit Loan, or explore a viatical settlement all covered in information below.
Once you've finished treatment and reached remission, the window for traditional life insurance resumes however the timing and expense depend greatly on your specific history. Insurance providers evaluate cancer survivors on several factors: staging, grade, and histology matter substantially most insurers need 210 years of tidy post-treatment history younger medical diagnosis can signal higher reoccurrence threat to underwriters surgical treatment alone vs.
With over 18 million cancer survivors in the United States, insurance providers have actually built more nuanced underwriting models that show the truth that many survivors live long, full lives. Getting several quotes from several insurance companies is critical, due to the fact that underwriting standards differ substantially company to business. For particular resources for your cancer type, visit our cancer financial resources section or evaluate all financial help options for cancer patients.

Latest Posts

Choosing the Right Expert High Risk Underwriting Expertise
Empathy-Driven Medical Underwriting Best Practices
Current Criteria for HIV Health Protection