All Categories
Featured
Could High Risk Life Insurance Become Affordable?

Essential Insurance Solutions for Complex Needs Trusts
Evaluating Current Risk Profiles for Chronic Conditions
Table of Contents
Amongst the numerous difficulties for households is ensuring there will constantly be sufficient money to provide life time care for their special needs children. The expenses are daunting: therapies, real estate, healthcare, and education, to name just a couple of. One method to plan for this difficulty is to establish a special needs trust.
A service for them is to money an unique needs trust with life insurance coverage. In these circumstances, a parent will take out a life insurance coverage policy on his life to make sure that once he dies, adequate funds will be offered to care for the special needs child. The trust is the beneficiary of the life insurance policy, so the funds from the death advantage go straight to the trust when the insured person passes away.
The purpose of life insurance, in any circumstance, is to offer instant funds to a household when its primary breadwinner dies all of a sudden. This will make sure that the enduring member of the family can fulfill their basic needs without exhausting their cost savings or entering into debt. Having enough capital is critically crucial to households with special needs children.
Additionally, the survivor benefit of a life insurance coverage policy flows to the trust quickly and is typically without taxation. The amount of the survivor benefit is ensured and delivered as cash (not securities or bonds), so it is exempt to the ups and downs of the stock market.
Local Insurance ExpertsComprehensive Health Coverage for Global Travel
If your policy is too little and you experience health problems later, you risk of ending up being uninsurable and won't be able to buy more. Understand the various types of life insurance. To money an unique requirements trust, the finest choice is some type of irreversible life insurance coverage, which will guarantee to pay the survivor benefit to the trust no matter when you die.
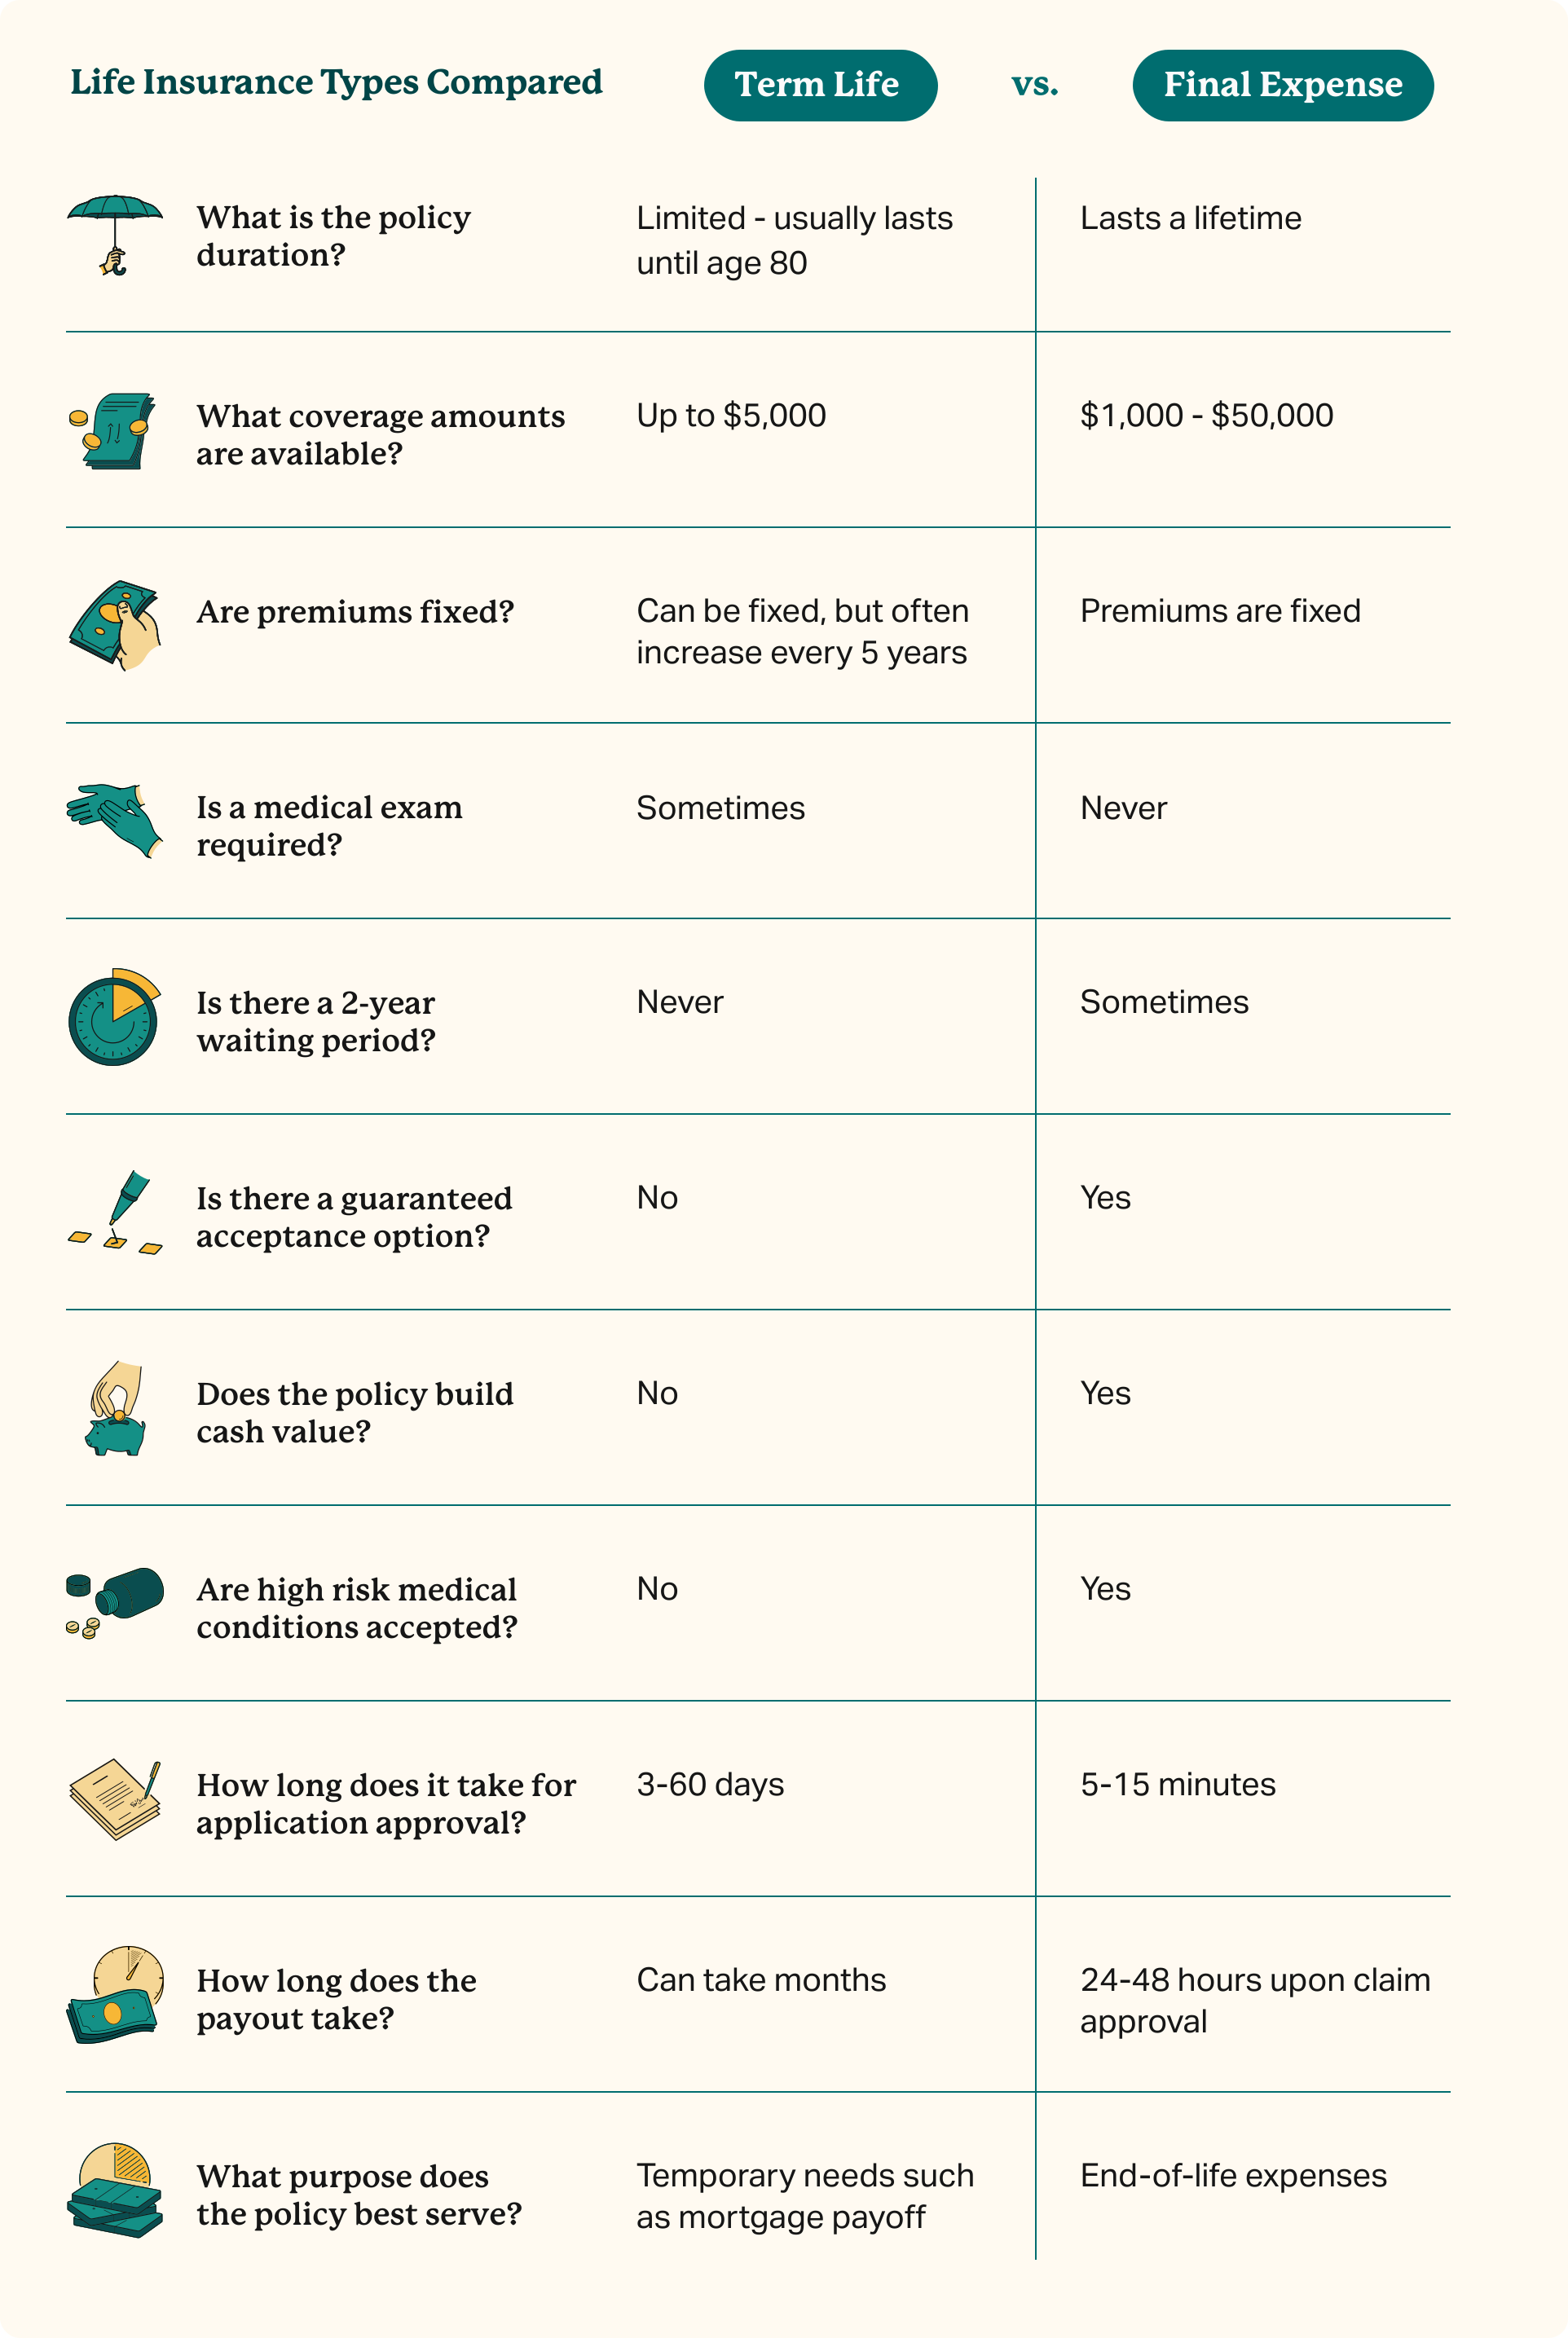
You risk of outliving the policy, with the outcome that the trust will no longer be moneyed by the death benefit once you're gone. Couples will frequently acquire what's known as a second-to-die or survivorship life insurance policy, which covers the lives of both parents. The policy will pay the death benefit to the unique requirements trust as soon as the surviving moms and dad passes away.
Finally, do not wait! Perhaps your health is at its finest right now, depending upon your age and health. If so, now is the very best time to apply, for the highest rating and most affordable premiums. A local special requirements planner can help you decide whether moneying a trust with life insurance coverage is an excellent financial investment for your household, and if so, just how much.
David M. Cordell, Ph. D., CFP, CFA, CLU, is director of financing programs at the University of Texas at Dallas. Thomas P. Langdon, J.D., LL.M., CFP, CFA, is teacher of organization law at Roger Williams University in Bristol, Rhode Island. Parents of kids with autism, Down syndrome, and other income-limiting physical or psychiatric conditions bear a special problem that is both monetary and psychological.
Navigating Impaired Risk Insurance Underwriting in 2026
SNTs are created to protect properties that can be utilized for the advantage of a specific with special requirements who is receiving state help due to his/her condition. Offered the recent modifications in earnings tax laws effective January 1, 2013, life insurance has actually become a more appealing funding mechanism for SNTs.
Many of the standard transfer techniques, however, pose distinct planning difficulties when unique needs individuals are involved. A parent could make an inter-vivos or testamentary transfer of possessions straight to an unique needs kid, but receipt of a direct transfer might disqualify the child from receiving needs-based federal government benefits. An alternative to transferring possessions to the special needs specific is to disinherit him or her so that the private qualifies for federal government benefits.
Another method is to leave properties to a 3rd party (such as a brother or sister, cousin, or close family friend) who assures to use those assets for the advantage of the kid. The obvious drawback to this technique is that, while well intentioned, it is not legally enforceable and might lead to depriving the child making use of those assets.
Local Insurance ExpertsGenerally, a special requirements trust is developed as a third-party supplemental needs trust. SNTs are produced and funded by somebody besides the recipient (generally the moms and dad), and expressly state that the trustee might just distribute trust earnings and properties for the recipient's requirements in excess of services supplied by the government.

Latest Posts
Could Impaired Risk Plans Secure Your Legacy?
Could High Risk Life Insurance Become Affordable?
Underwriting Updates for Chronic Conditions