All Categories
Featured
Could High Risk Life Insurance Become Affordable?

Essential Insurance Solutions for Complex Needs Trusts
Underwriting Updates for Chronic Conditions
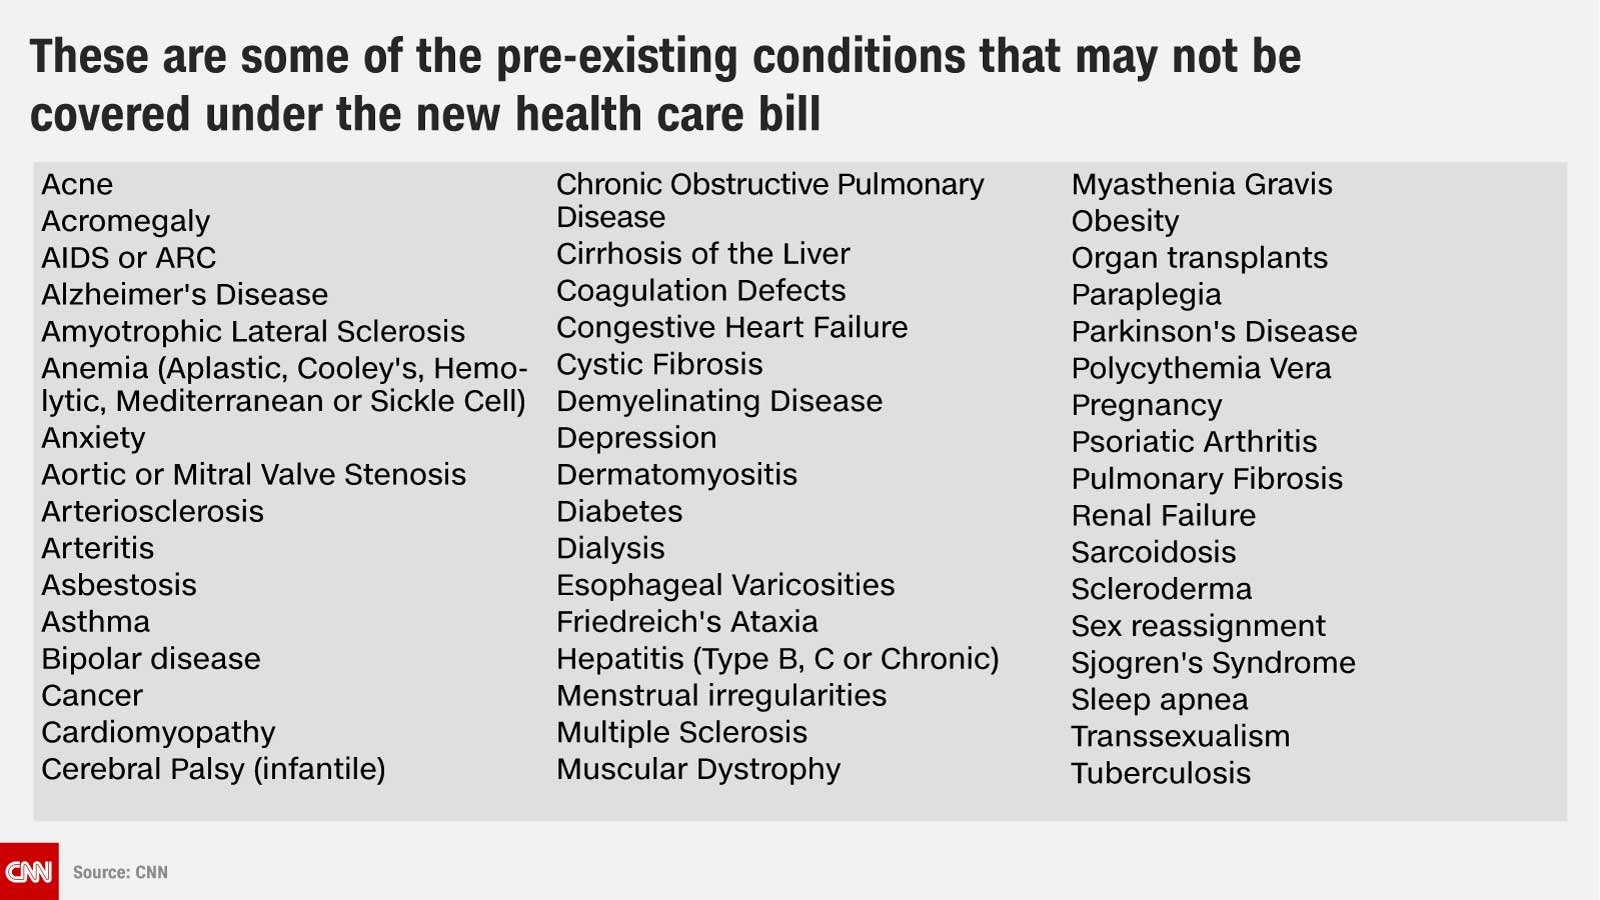
Medical conditions that are stable and well-managed occupy a fundamentally various underwriting position than conditions that are actively unsteady, just recently complicated, or inadequately treated even when the medical diagnosis name is the same. Conditions that consistently develop underwriting friction throughout the majority of carriers include current or active cancer in treatment (where most carriers hold off till treatment is total and remission is established for a specified duration), active symptomatic cardiac arrest or extremely current significant cardiac events, advanced kidney disease with significantly lowered function, severe COPD with documented oxygen reliance, and complex autoimmune conditions with active organ involvement.
Our resource on life insurance for autoimmune disease covers the basic autoimmune underwriting framework, which uses across the classification with condition-specific variations. Blood clot conditions and deep vein apoplexy history present specific underwriting questions around reoccurrence risk and anticoagulant treatment; our resource on life insurance for embolism history covers this discussion. Modern underwriting utilizes electronic prescription databases that offer a history of filled prescriptions, generally covering several years, that the provider questions as part of the underwriting evaluation. When the application disclosure is inconsistent with what that database reveals, the carrier translates the inconsistency as an issue either a considerable medical issue that was omitted from disclosure, or, in the worst analysis, intentional misrepresentation.
Each of these creates an inconsistency that slows underwriting, sets off additional inquiries, and in some cases produces a conservative result that would not have accompanied total initial disclosure. The service is accurate and complete disclosure at the application phase not omitting medications since they appear small or due to the fact that the candidate has actually stabilized them as part of life.
Impaired Risk Specialized CoverageContext ought to be provided where appropriate a broker cover letter that discusses a medication's indicator, the period of use, and the stability of the underlying condition transforms a possible warning into a recorded, contextualized disclosure that underwriters examine properly rather than conservatively. Our resource on what is MIB in insurance coverage covers how underwriting databases produce cross-referencing that makes complete disclosure not simply ethical however almost required for the very best result.
Specialized Coverage for Cancer Survivors
Stable, cured depression with consistent treatment and medication management and no hospitalizations typically produces standard to slightly ranked outcomes at lots of carriers. The aspects that create major underwriting friction are current hospitalizations, recent suicide efforts (which produce posts ponement or declines at many providers for defined durations), extreme instability, several medication modifications within a short window, and patterns recommending ongoing practical impairment.
The provider that evaluates mental health history most favorably is typically one with particular underwriting experience in behavioral health danger not the provider with the very best general market premium. Compound usage history follows the same pattern reasoning. A DUI from 7 years ago without any subsequent incidents produces a very different underwriting action than 2 DUIs within the past three years, even when both candidates explain themselves as "having had a drinking problem in the past." Continuous compound usage disorder, current inpatient treatment, and several substance-related events produce the most conservative responses.
Life insurance coverage underwriting evaluates non-medical factors that affect death danger with the very same principle that uses to medical factors: intensity, pattern, and provider appetite figure out the result. Dangerous occupations commercial diving, offshore oil and gas work, mining, explosive handling develop underwriting friction since they represent elevated mishap death threat that standard premium designs may not properly cost.
High-risk things private air travel, motorsports, skydiving, rock climbing up at competitive levels are evaluated likewise: the level and frequency of participation, the training and accreditation level of the participant, and the carrier's existing appetite for the specific activity determine the outcome. Some providers have well-developed flat extra schedules for particular things that produce insurable coverage with defined premium additions; others decline the avocation entirely.
An official decrease at one carrier produces an MIB notation that subsequent providers can see when they query the database as part of their underwriting review. When an application divulges a prior decline (as the majority of applications need), the new provider's underwriter will assess not just the current application but the context of the previous decrease: why did the previous carrier decrease? Is the current provider being asked to take on a danger that an advanced peer carrier currently evaluated and turned down?

Latest Posts
Could Impaired Risk Plans Secure Your Legacy?
Could High Risk Life Insurance Become Affordable?
Underwriting Updates for Chronic Conditions