All Categories
Featured
Could High Risk Life Insurance Become Affordable?

Essential Insurance Solutions for Complex Needs Trusts

Integrating Life Insurance with Special Needs Planning
It's normally called something along the lines of a "Surefire Issue" policy. Anyone is qualified to get this type of policy, no matter health history or present health status. Find out more about life insurance coverage options without a medical examination. Corebridge Direct offers Surefire Problem Whole Life Insurance Coverage, which offers ensured coverage for those ages 50 to 85 and uses coverage for up to $25,000, to cover expenditures like funeral expenses, charge card debt, and medical expenses.
Life Insurance for Cancer Survivors
In other cases, choosing for a life insurance coverage strategy without medical underwriting may make more monetary sense for you and your family. Life insurance coverage is an important asset in any case considering that it secures your loved ones when you pass on.
2. The AGL GIWL policy referenced provides a restricted death advantage in the very first two years of the policy. Needs to death occur in the first 2 years, a death advantage will be equal to 110% of the premiums paid. In case of suicide, the death advantage is limited to a refund of premiums only.
Life Insurance for Cancer Survivors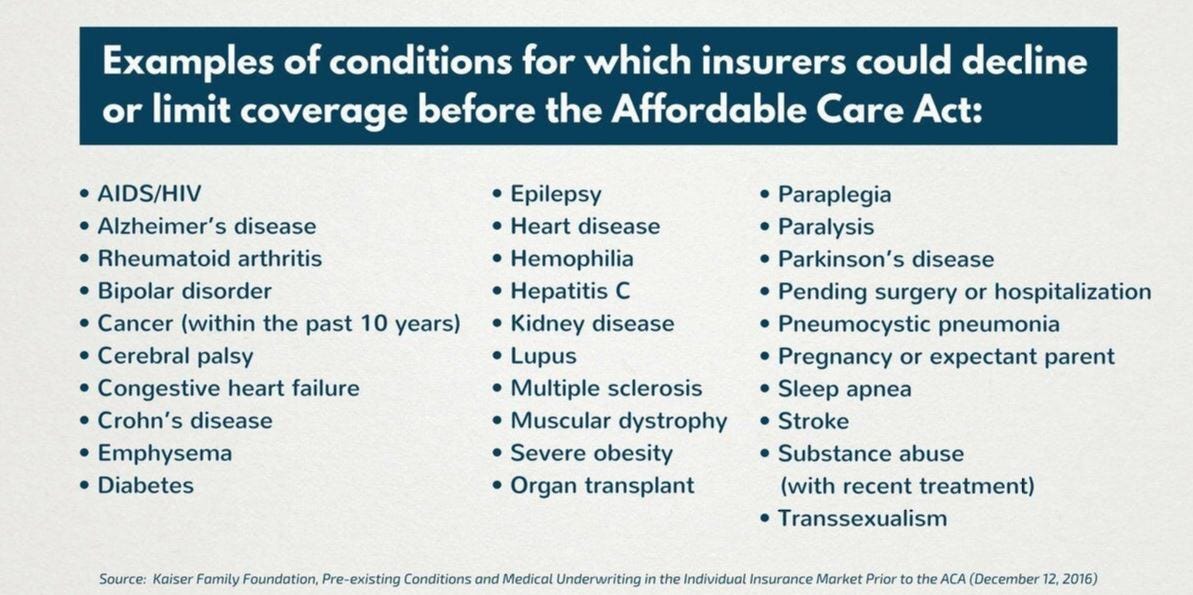
This content is limited to site members. If you are an existing user, please log in. New users might sign up listed below.
On the planet of Life Insurance coverage, not all candidates fit the mold of a "standard" danger. Numerous people deal with health difficulties or participate in high-risk activities that can affect their eligibility for protection. This is where impaired risk underwriting enters play. As a representative, understanding the technique around impaired risk is crucial to providing detailed protection for your customers.

Latest Posts
Could Impaired Risk Plans Secure Your Legacy?
Could High Risk Life Insurance Become Affordable?
Underwriting Updates for Chronic Conditions